

Blog
Credit Analyst Career Path: How to Start and Grow in Credit Analysis?

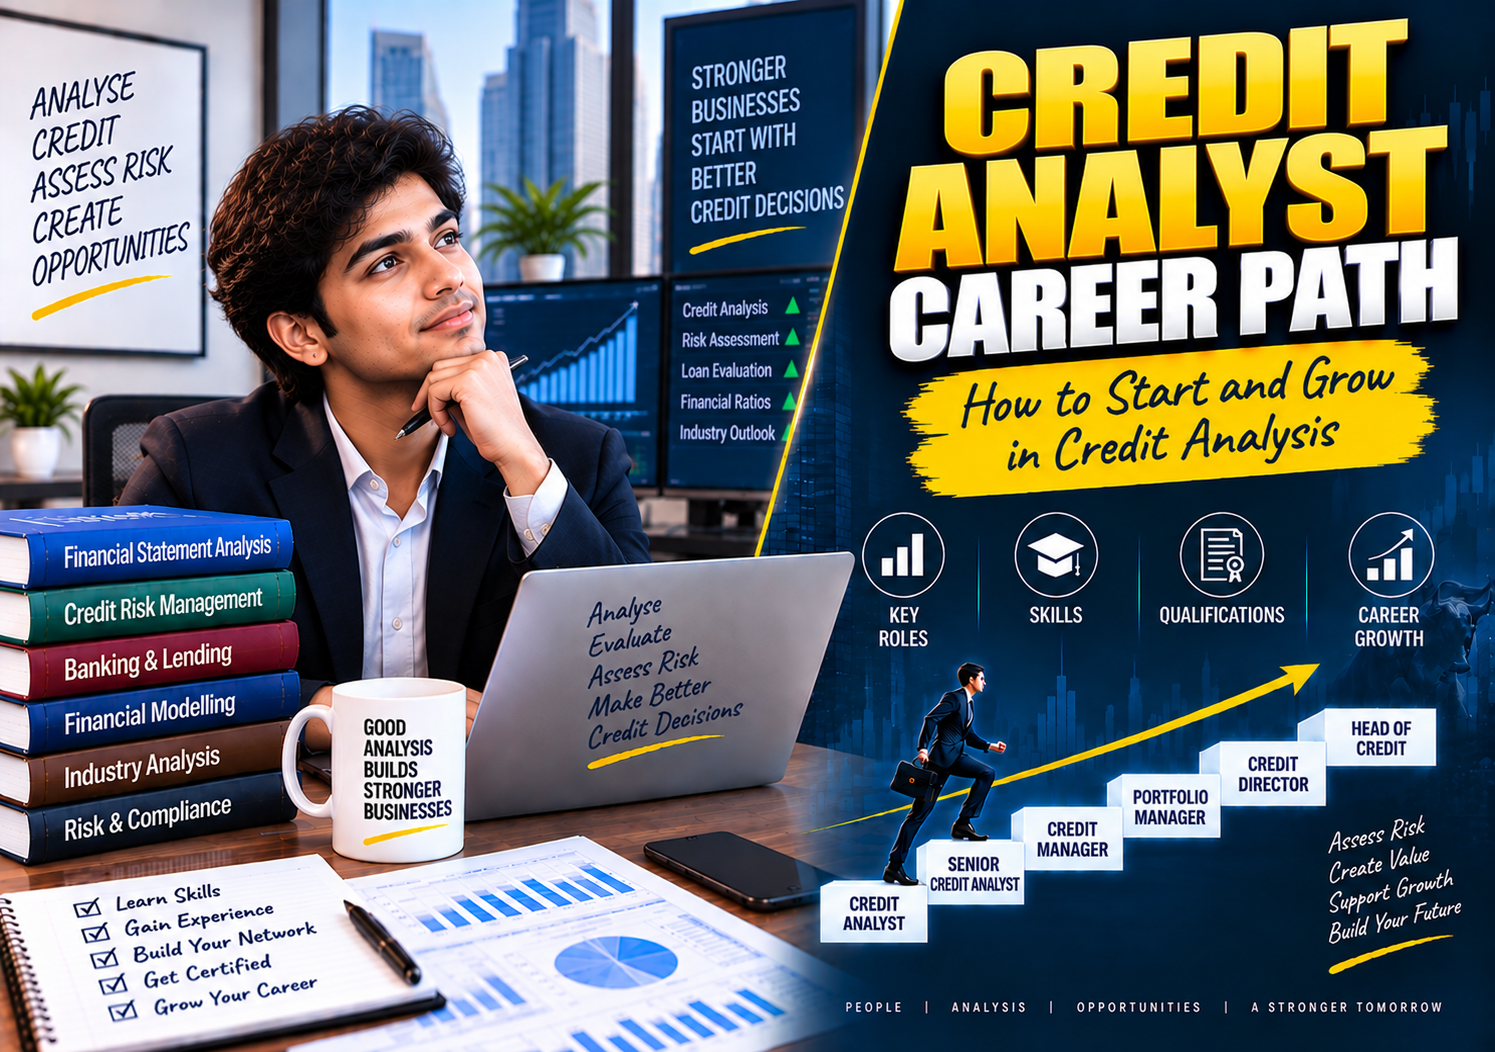
A credit analyst career path is built around one central question: Can this borrower repay what they owe?
Credit analysts examine financial statements, cash flows, debt, industry conditions and other information to assess creditworthiness. Their work can influence lending decisions, loan terms, credit ratings and portfolio risk.
For commerce students, credit analysis can be a practical finance career because it combines accounting, financial analysis, business research and risk assessment. You can start with a B.Com or another relevant degree and build specialized skills as you gain experience.
The career can lead from Credit Analyst to Senior Analyst, Credit Manager, Portfolio Manager, Credit Director and other senior finance or banking roles.
What Does a Credit Analyst Do?
A credit analyst evaluates the financial strength of a borrower and helps determine the level of credit risk involved.
Depending on the employer, the borrower could be an individual, small business, large corporation or financial institution.
Typical responsibilities include:
- Reviewing income statements, balance sheets and cash flow statements
- Analysing debt and repayment capacity
- Calculating financial ratios
- Reviewing industry and economic conditions
- Assessing management and business quality
- Building cash flow projections
- Monitoring existing borrowers
- Preparing credit reports or credit memos
- Recommending whether credit should be approved, modified or declined
In commercial banking, analysts may also work with relationship managers and credit committees. In credit rating agencies, the focus can be on assessing the creditworthiness of companies or debt instruments.
The work is not simply about finding a company’s weaknesses.
A good credit analyst asks a broader question:
What could prevent this borrower from repaying, and how much protection does the lender have if conditions deteriorate?
Credit Analyst Career Path at a Glance
The exact progression differs between banks, rating agencies, NBFCs, corporations and investment firms. A common progression looks like this:
| Career Stage | Typical Roles | Main Responsibility |
|---|---|---|
| Entry level | Junior Credit Analyst, Credit Analyst | Financial analysis and credit assessment |
| Early career | Credit Analyst, Senior Credit Analyst | Underwriting, credit memos and portfolio monitoring |
| Mid career | Credit Manager, Portfolio Manager | Larger portfolios and credit decisions |
| Senior | Senior Credit Manager, Credit Director | Policy, complex exposures and team leadership |
| Executive | Head of Credit, Senior Credit Executive | Credit strategy and risk governance |
Not every professional follows the same route. For example, commercial banking can lead toward portfolio management or relationship management, while rating-agency professionals may progress from analyst to senior analyst and then into broader analytical or leadership positions.
1. Starting as a Credit Analyst
At the beginning of your career, much of your time may be spent understanding financial information.
You might analyse:
- Revenue and profitability
- Debt levels
- Cash flows
- Working capital
- Interest payments
- Existing loans
- Financial ratios
- Industry conditions
You may also prepare a credit memo that summarizes the borrower’s financial position, key risks and your recommendation.
This stage is about building judgment.
It’s one thing to calculate a debt-to-equity ratio. It’s another to understand why the ratio matters for that particular borrower.
2. Senior Credit Analyst
After gaining experience, the work becomes more complex.
You may handle larger borrowers, more complicated financial structures or bigger credit exposures.
Responsibilities can include:
- Reviewing junior analysts’ work
- Performing detailed borrower assessments
- Building financial projections
- Analysing repayment scenarios
- Reviewing loan covenants
- Monitoring credit portfolios
- Preparing recommendations for senior decision-makers
At this stage, you should be able to explain your conclusion clearly.
If you recommend approving a loan, you should be able to explain why the risk is acceptable and what safeguards are available.
If you recommend declining it, you should be able to identify the specific weaknesses behind that decision.
3. Credit Manager and Portfolio Manager
The next stage often brings more responsibility for portfolios and people.
A Credit Manager may review larger or more complex credit decisions, establish internal processes and supervise analysts.
A Portfolio Manager may monitor a group of borrowers or credit exposures over time.
This changes the nature of the job.
You are no longer looking only at one borrower. You need to understand how multiple exposures behave and whether the overall portfolio has excessive concentration or risk.
Some commercial banking career paths move from credit analysis into portfolio management and later relationship management or senior credit leadership.
4. Senior Credit Leadership
With substantial experience, professionals can move into roles such as:
- Credit Director
- Head of Credit
- Chief Credit Officer
- Senior Risk Management roles
At this level, the focus becomes broader.
Senior leaders may be involved in:
- Credit policies
- Risk appetite
- Portfolio quality
- Large credit approvals
- Risk governance
- Team management
- Regulatory requirements
- Strategic lending decisions
The job gradually shifts from analysing individual financial statements to managing the quality and direction of the organization’s credit business.
Where Can Credit Analysts Work?
Credit analysis is not limited to traditional banks.
Potential employers include:
- Commercial banks
- NBFCs
- Credit rating agencies
- Investment firms
- Insurance companies
- Corporate finance departments
- Financial services companies
- Credit research teams
- Fintech companies
The work can differ significantly between these organizations.
A bank credit analyst may evaluate whether a company should receive a loan.
A rating analyst may assess the creditworthiness of an issuer or debt transaction.
An investment-oriented credit analyst may study bonds and default risk as part of investment research. CFA Institute distinguishes credit analysts from equity analysts partly because credit analysis focuses on bonds and default risk rather than primarily on equity performance.
What Qualifications Do You Need?
There is no single qualification required for every credit analyst role.
Relevant academic backgrounds include:
- B.Com
- BBA
- Finance
- Economics
- Accounting
- Business administration
- Mathematics or statistics for more quantitative roles
A finance, accounting or economics background can be particularly useful because much of credit analysis starts with understanding financial statements.
CFA Institute also notes that strong academic backgrounds in finance, economics or accounting can support entry into credit-related analytical careers.
B.Com
B.Com is a practical starting point for commerce students.
Subjects such as accounting, financial management, economics and business law can provide useful foundations.
But don’t stop with the degree.
Credit analysis is a practical skill, and employers need people who can actually interpret financial information.
CA
CA can be useful for credit analysis because of its strong foundation in accounting, auditing and financial reporting.
A CA’s understanding of financial statements can be valuable when assessing the financial health of borrowers.
CMA
CMA can also provide relevant knowledge through management accounting, costing and financial management.
This can be useful when analysing business performance and understanding how costs and profitability affect repayment capacity.
CFA
CFA can be relevant for credit research and investment-oriented roles, particularly when the work involves financial markets, fixed income and investment analysis. CFA Institute identifies credit analysis as one of the research career areas within the investment industry.
The right qualification depends on the role you want. Don’t collect certifications without developing actual credit-analysis ability.
Skills You Need to Become a Credit Analyst
1. Financial Statement Analysis
This is probably the most important technical foundation.
You should be able to read:
- Income statements
- Balance sheets
- Cash flow statements
But reading isn’t enough.
You need to connect the statements.
For example, a company may report strong accounting profits while generating weak operating cash flow. A credit analyst should investigate why.
2. Ratio Analysis
You should understand ratios related to:
- Liquidity
- Leverage
- Profitability
- Coverage
- Efficiency
The goal isn’t to memorize formulas.
The real skill is understanding what the ratios say about the borrower’s ability to meet financial obligations.
3. Excel and Financial Modelling
Excel is widely used for credit analysis.
You may use it to build:
- Cash flow projections
- Debt schedules
- Ratio analysis
- Sensitivity analysis
- Scenario models
Imagine a company has significant debt coming due over the next three years.
You could model its expected cash flows and test what happens if revenue falls or interest costs increase.
That is much more useful than simply looking at historical financial statements.
4. Industry Research
A company’s financial statements don’t tell the whole story.
Consider two businesses with similar financial ratios.
One operates in a stable industry with predictable demand.
The other operates in a highly cyclical industry where revenue can fall sharply during an economic slowdown.
The credit risk may be very different.
5. Critical Thinking
Credit analysis requires judgment.
You need to question unusual numbers, investigate inconsistencies and identify information that may change your conclusion.
6. Communication
Credit analysts often have to explain their conclusions to managers, credit committees or other stakeholders.
CFA Institute identifies communication, attention to detail, analytical competency and critical thinking as transferable skills across finance careers.
Being able to explain a complicated financial situation in simple language can become a major career advantage.
7. Technology and Data Skills
Technology skills are becoming more relevant across finance.
Depending on the role, useful skills can include:
- SQL
- Python
- Power BI
- Data visualization
- Statistical analysis
CFA Institute’s 2026 research on finance employers also points to growing demand for AI, coding and data skills alongside traditional financial analysis and human judgment.
You don’t need to become a programmer before applying for your first credit analyst job. Start with strong financial analysis and Excel, then add technology skills based on the roles you target.
How to Start a Credit Analyst Career After B.Com?
If you’re a commerce student, you can build your path in a fairly straightforward sequence.
Step 1: Master Financial Statements
Don’t just study accounting for exams.
Take a listed company’s annual report and try to understand how its income, assets, debt and cash flows fit together.
Step 2: Learn Credit Ratios
Understand liquidity, leverage, profitability and debt-servicing measures.
Then ask what each ratio actually tells you.
Step 3: Improve Excel
Learn formulas, lookup functions, pivot tables, charts and basic financial modelling.
Step 4: Learn How Lending Works
Understand concepts such as:
- Loan structures
- Interest
- Collateral
- Covenants
- Repayment schedules
- Default
- Credit limits
Step 5: Practise Credit Memos
Take a public company’s financial statements and write a short fictional credit assessment.
Clearly label it as an illustrative exercise, not a real lending recommendation.
Step 6: Look for Relevant Internships
Search for internships and entry-level roles in:
- Banks
- NBFCs
- Rating agencies
- Financial services firms
- Credit research teams
Step 7: Add a Relevant Qualification
Once you understand the type of credit work you want, decide whether CA, CMA, CFA, FRM or another specialized program makes sense for your career plan.
What Does a Credit Analyst Look for in a Company?
A useful way to think about credit analysis is through five questions.
Can the company generate cash?
Profit matters, but lenders also need to understand actual cash generation.
How much debt does it already have?
A profitable business can still face pressure if its debt obligations are too large.
How stable is the business?
A company dependent on one customer, one product or a highly cyclical market may carry different risks from a diversified business.
What happens if conditions worsen?
Credit analysis should not rely only on the base-case forecast.
What protection does the lender have?
Depending on the transaction, this may involve collateral, covenants, guarantees or other structural protections.
The strongest credit analysis doesn’t simply say “This company looks profitable.”
It asks what could cause repayment capacity to weaken.
Credit Analyst vs Financial Analyst
The titles sound similar, but the focus is different.
| Credit Analyst | Financial Analyst |
|---|---|
| Focuses heavily on creditworthiness | Broader financial analysis |
| Studies default and repayment risk | May analyse business performance and investments |
| Often works with lenders or credit teams | Can work across corporate finance and investment roles |
| Analyses debt capacity | May analyse profitability, valuation and forecasts |
| Credit decisions are central | Investment or business decisions may be central |
There can be overlap. CFA Institute notes that credit and other financial research roles use financial analysis, modelling and data interpretation, but their ultimate objectives can differ.
Common Mistakes Beginners Make
Focusing Only on Profit
A company can report profits and still have cash-flow problems.
Memorizing Ratios Without Interpretation
Ratios are signals, not final answers.
Ignoring the Industry
Financial numbers make more sense when viewed in the context of the business model and industry.
Treating Historical Numbers as the Future
Past performance provides evidence, but credit analysis also requires thinking about future repayment capacity.
Learning Excel Without Learning Finance
A technically impressive spreadsheet doesn’t make a good credit analyst.
Ignoring Communication
Your recommendation is useful only when decision-makers understand the reasoning behind it.
Where Can the Credit Analyst Career Path Lead?
Credit analysis can become a foundation for several finance careers.
Possible directions include:
Credit Analyst → Senior Credit Analyst → Credit Manager → Credit Director
Another route could be:
Credit Analyst → Portfolio Analyst/Manager → Senior Portfolio Role
Professionals in investment-oriented credit research may follow a different progression through research and ratings roles.
Credit experience can also provide a foundation for related careers in risk management, commercial banking, corporate finance and financial research.
The best route depends on what you enjoy.
If you like analysing borrowers and lending decisions, staying in credit may make sense. If you become more interested in markets, investments or broader risk management, your credit background can provide a useful starting point for moving into those areas.
How to Build a Long-Term Credit Analysis Career?
The early stage of a credit analyst career is mainly about becoming technically reliable.
Learn to analyse financial statements.
Understand cash flow.
Build strong Excel skills.
Learn how debt works.
Then develop judgment.
As you progress, employers will expect more than accurate calculations. They’ll want someone who can spot risks, challenge assumptions, explain findings and make sensible recommendations.
That is what turns a person who can analyse numbers into a credit professional who can make financial judgments.
Build Your Credit Analysis Foundation with Master Minds
Credit analysis depends heavily on strong foundations in accounting, financial management, costing and business performance. For commerce students considering CA or CMA, these subjects can provide useful preparation before moving into specialized careers such as credit analysis, credit risk, banking and financial research.
Master Minds India focuses on professional commerce education, while its CA & CMA courses can help students build the academic foundation needed for longer-term finance careers. The next step is to combine that foundation with practical skills in financial statement analysis, Excel, credit assessment and business research.
